By Syed Muhammad Raza Shah, Insurance Consultant — 12+ years advising UAE residents and businesses on medical, motor and general insurance. Last updated: October 2026.
In short: Car insurance for old cars in UAE: many insurers still offer comprehensive cover up to about 10 years, and some go further with inspection. The gap between comprehensive and third-party is often only a few hundred dirhams, so check the whole market before settling for third-party.
Ramesh is a 51-year-old accountant in Sharjah who has driven the same Japanese saloon since 2014. It has 240,000 km on the clock and has never let him down. Every year he renewed comprehensive cover with the same insurer. In 2025 the renewal quote said the car could only be insured for third-party only, because it had passed the insurer’s age limit for comprehensive cover.
He switched to third-party to save time. Eight months later, a hailstorm-and-rain evening in Sharjah left his windscreen cracked and a tree branch through the rear window. Repairs came to AED 3,700, all out of his own pocket. A week later a friend mentioned that two other insurers would still have offered him comprehensive cover, one of them at AED 1,450 with a market-value sum insured of AED 14,000.
Ramesh’s situation is increasingly common. Used vehicles make up 63.58% of the UAE motor insurance market, and that segment is growing faster than new cars, at 9.74% a year (Mordor Intelligence). Yet many drivers don’t know how insurers treat older cars, or what options they have when their usual insurer says no.
This guide explains car insurance for old cars in the UAE: why comprehensive cover gets harder with age, how insurers value an older car, what it costs, and how to decide between comprehensive, third-party and the options in between.
Car Insurance for Old Cars in the UAE: Why Insurers Treat Them Differently
- Parts get harder to find and more expensive. Discontinued parts and long import times raise repair costs.
- Repair costs rise relative to value. Under the UAE’s unified motor policy, a car is a total loss when repair costs exceed 50% of its pre-accident value. As the value falls, more accidents become total losses.
- Mechanical wear increases claim frequency. Older cars have more fires, breakdowns and “is this accident or wear?” disputes.
- Risk-based pricing. In 2026, insurers are pricing more precisely by vehicle age and type. Older and luxury vehicles face higher relative costs, as industry experts told Emirates 24|7 in July 2026.
What Age Limits Apply?
There’s no single legal age limit. Each insurer sets its own rules. Typical market practice:
| Car age | Comprehensive availability | Agency repair |
|---|---|---|
| 0 – 3 years | Widely available | Widely available |
| 4 – 7 years | Widely available | Limited |
| 8 – 10 years | Available from many insurers, sometimes with inspection | Rare |
| 11 – 15 years | Selected insurers only, often with inspection and conditions | No |
| 15+ years | Rare; mostly third-party only (classic car specialists excepted) | No |
Rules vary by insurer and model.
Key point: if one insurer declines comprehensive cover because of age, others may still offer it. Ask a broker to check the whole market.
How Insurers Value an Older Car
Your sum insured (the car’s insured value) matters, because it’s what you’re paid if the car is written off.
- Insurers usually base the sum insured on current market value, not what you paid.
- The unified comprehensive policy applies a depreciation schedule for private vehicles:
| Vehicle age | Depreciation (per unified policy) |
|---|---|
| Year 1 | 0% |
| Year 2 | 5% |
| Year 3 | 10% |
| Year 4 | 15% |
| Year 5 | 20% |
| Year 6+ | 30% |
Tip: If your car is in unusually good condition or has low mileage, give evidence such as service history, photos or a recent valuation, and ask for a sum insured that reflects it. Over-insuring doesn’t help: you’re normally paid market value regardless.
What Does Insurance Cost for an Older Car?
| Car | Age | Comprehensive (non-agency) | Third-party only |
|---|---|---|---|
| Compact saloon, market value AED 18,000 | 9 years | AED 1,100 – 1,700 | AED 750 – 1,300 |
| Mid-size SUV, market value AED 35,000 | 8 years | AED 1,500 – 2,400 | AED 900 – 1,500 |
| Luxury saloon, market value AED 45,000 | 10 years | AED 2,500 – 4,500 (if offered) | AED 1,200 – 2,200 |
Indicative ranges only — actual premiums depend on your profile, insurer, and current market conditions. Compulsory third-party cover for a 4-cylinder saloon was quoted at about AED 750–1,300 in July 2026.
For many older mainstream cars, the gap between comprehensive and third-party is only a few hundred dirhams. That’s often worth paying.
Comprehensive vs Third-Party for an Older Car: How to Decide
Use the “10% rule of thumb” as a starting point:
If the extra cost of comprehensive over third-party is less than about 10% of the car’s market value, comprehensive is usually worth it.
| Market value | Extra cost of comprehensive | Rule suggests |
|---|---|---|
| AED 30,000 | AED 600 (2%) | Comprehensive |
| AED 15,000 | AED 500 (3.3%) | Comprehensive |
| AED 8,000 | AED 900 (11%) | Third-party may make sense |
Also consider:
- Could you replace the car from savings tomorrow? If not, keep comprehensive.
- Where do you park? Open parking means more exposure to weather, hail, falling objects and theft.
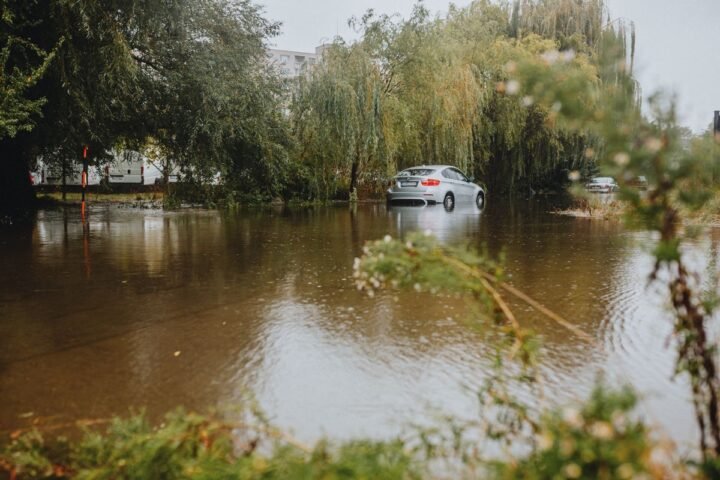
- Floods and weather. Only comprehensive with natural perils covers your own car in a flood. See Car Insurance Flood Cover in UAE.
Options When Comprehensive Isn’t Available
- Ask other insurers. Age limits differ widely.
- Accept an inspection. Many insurers will cover older cars after a physical check.
- Accept a higher deductible. This can make an insurer more willing to offer cover.
- Third-party with add-ons. Many TPL policies offer add-ons such as personal accident for the driver and passengers, roadside assistance and Oman cover. These don’t cover damage to your own car, but they add useful protection.
- Classic car specialists. For older collectable cars, look for specialist agreed-value policies.
Keeping an Older Car Insurable
- Keep a full service history. It helps at inspection and valuation.
- Fix warning lights and leaks promptly. Insurers may decline cars with visible defects.
- Keep tyres, lights and brakes in good condition. These are safety items that can come up in claims disputes.
- Keep the car’s registration and inspection current.
Three Owner Scenarios
Scenario 1: 9-year-old Japanese saloon, market value AED 16,000, parked on the street
- Comprehensive (non-agency): about AED 1,300
- Third-party: about AED 900
- Extra for comprehensive: AED 400, or 2.5% of value
- Recommendation: Comprehensive with natural perils. One windscreen, theft or flood claim would cost more than the difference.
Scenario 2: 12-year-old European luxury saloon, market value AED 28,000, garage parked
- Comprehensive: offered by only a few insurers, about AED 3,200, with inspection and a higher deductible
- Third-party: about AED 1,500
- Extra for comprehensive: AED 1,700, or 6% of value
- Recommendation: Borderline. Comprehensive makes sense if you’d struggle to cover a large repair. Luxury parts are expensive even on older cars.
Scenario 3: 16-year-old pickup used on the family farm, market value AED 9,000
- Comprehensive: mostly unavailable
- Third-party: about AED 1,100
- Recommendation: Third-party plus personal accident and roadside assistance. Set aside savings for repairs.
Indicative figures for illustration only.
Older Cars and the Total-Loss Trap
Because older cars have lower values, more accidents become total losses. Under the unified policy, a car is written off when repairs exceed 50% of its pre-accident value. For a car worth AED 16,000, that’s AED 8,000, which a moderate front-end collision with airbag deployment can easily exceed.
What that means for you:
- Your payout is the market value, not the repair cost.
- Sentimental value isn’t insured.
- If you’d rather repair than accept a total loss, ask about keeping the salvage. It’s deducted from the payout, and you arrange the repair yourself.
Inspection: What Insurers Check on Older Cars
If an insurer asks to inspect an older car before offering comprehensive cover, expect checks on:
- Existing body damage (photographed and excluded if present)
- Tyres, lights and windscreen condition
- Warning lights on the dashboard
- Odometer reading and service history
- Modifications (aftermarket wheels, tints, performance parts)
- Chassis number match with registration
Tip: Fix small, cheap defects before inspection. A cracked windscreen or bald tyres can lead to refusal or exclusions.
Modified and Imported Older Cars
- Modifications (performance tuning, body kits, suspension changes) must be declared. Undeclared modifications can void a claim.
- Imported used cars (especially from North America) may have salvage or flood history. Some insurers ask for a history report and may restrict cover.
- Classic and collectable cars often suit agreed-value policies from specialist providers, where the payout is fixed in advance.
Selling or Scrapping an Older Car: Insurance Steps
When the time comes to sell or scrap an older car:
- Don’t cancel insurance until ownership has been transferred or the car is de-registered. You remain liable while the car is registered to you.
- Ask for a pro-rata refund for the unused period after transfer. Many insurers refund unused premium if no claims were made.
- Request an NCD letter before cancelling, so your claim-free history moves to your next car.
- Remove personal documents and toll tags (e.g., Salik) from the vehicle.
- Keep the transfer or de-registration certificate in case of later fines or claims.
These simple steps protect your no-claims discount and avoid paying for cover you no longer need.
Roadside Assistance: Especially Valuable for Older Cars
Older cars break down more often. Roadside assistance, included with many comprehensive policies and available as an add-on to third-party cover, typically includes:
- Towing to a garage (within a distance limit)
- Battery boost and flat tyre change
- Fuel delivery if you run out
- Lockout service
- Sometimes Oman cover for breakdowns across the border
For an older car, the cost of one tow can equal the add-on premium. Check the number of call-outs allowed per year and the towing distance limit.
Older Cars and Oman Cover
Many UAE residents drive to Oman. UAE motor policies cover the UAE only unless extended. For older cars, especially on third-party policies, check whether an Oman extension is available and what it includes (own damage, third-party only, or both). Some insurers restrict extensions on older vehicles. Buying cover at the border is possible, but arranging it in advance is usually simpler.
Tip: Set a calendar reminder 30 days before renewal every year. Older cars are the most likely to be moved to third-party-only without much notice, and that gives you time to shop around.
Checklist of Documents for Insuring an Older Car
- Registration (Mulkiya) and valid inspection
- Service history and recent maintenance receipts
- Photos of all sides, interior and odometer
- Previous insurer’s certificate and NCD letter
- Details of any modifications
- Import history report (for imported vehicles)
Checklist
- ☐ I’ve checked comprehensive availability with at least three insurers
- ☐ My sum insured reflects current market value
- ☐ I’ve compared the extra cost against the 10% rule of thumb
- ☐ Natural perils included if I choose comprehensive
- ☐ TPL add-ons considered if I choose third-party
- ☐ Service history ready for any inspection
Frequently Asked Questions
Can I get comprehensive insurance for a car older than 10 years in the UAE?
Yes, from some insurers. Many UAE insurers offer comprehensive cover up to 10 years, and some go further, often subject to an inspection, a higher deductible or non-agency repair. If your current insurer offers only third-party, ask a broker to check other insurers, since age limits vary widely.
How much is car insurance for an old car in the UAE?
For an older mainstream car worth AED 15,000–35,000, comprehensive non-agency cover typically costs about AED 1,100–2,400 a year, while compulsory third-party costs about AED 750–1,500. Luxury and high-performance older cars cost more. These are indicative ranges only; actual premiums depend on your car, profile and insurer.
Is it worth getting comprehensive insurance for an old car?
Often yes. If the extra cost of comprehensive over third-party is less than about 10% of the car’s market value, and you couldn’t easily replace the car from savings, comprehensive is usually worth it. It’s also the only way to cover your own car against floods, storms, theft and accidents where you’re at fault.
How do insurers value an old car for a total loss claim in the UAE?
Insurers usually pay the car’s market value just before the loss, supported by the sum insured and the depreciation schedule in the unified comprehensive policy, which reaches 30% from year six for private cars. A car is treated as a total loss if repair costs exceed 50% of its pre-accident value.
Why did my insurer refuse comprehensive cover for my car?
Insurers set their own age and condition limits for comprehensive cover. Common reasons for refusal are vehicle age (often over 10–15 years), high mileage, visible defects, a history of major repairs, or a model with expensive, hard-to-find parts. Other insurers may still offer cover, sometimes after an inspection.
Does third-party insurance cover my own car if it’s old?
No. Third-party insurance only covers damage or injury you cause to other people and their property. It doesn’t cover damage to your own car from accidents, theft, fire, floods or storms, whatever the car’s age. For that you need comprehensive insurance.
Related Reading
- Agency Repair vs Non-Agency Repair: Which Car Insurance Should You Choose in UAE?
- Car Insurance Flood Cover in UAE
- Does Car Insurance Cover War or Missile Damage in the UAE?
Conclusion
An older car doesn’t automatically mean third-party only. Many insurers will still offer comprehensive cover, and for a mainstream model the extra cost is often only a few hundred dirhams, which is much less than a single windscreen, flood or theft loss. Check more than one insurer, make sure your sum insured reflects market value, and use the 10% rule to decide.
Your next step: before your next renewal, find your car’s market value and ask for both comprehensive and third-party quotes from at least three insurers. If your insurer has said no to comprehensive, send the details through the inquiry page and I’ll check the wider market for you.
Sources
- Mordor Intelligence, UAE Motor Insurance Market (used vehicles 63.58% share, 9.74% CAGR)
- CBUAE Rulebook, Unified Motor Vehicle Insurance Policy Against Loss and Damage (depreciation schedule; total loss definition)
- Emirates 24|7, “UAE motorists report rising vehicle insurance renewal premiums despite no claims”, July 2026
The opening scenario is a composite illustration based on typical cases; names and details are fictional. Age limits reflect common market practice and vary by insurer.

One comment